The Longevity Economy: Rethinking Work, Business and Opportunity in an Ageing World
Written by Admin • 2026-11-11 01:37:00
Topics
The longevity economy highlights how the global ageing population is reshaping business landscapes, consumer behavior, and workforce dynamics. It calls for enterprises to rethink traditional business models and create inclusive environments that recognize the value of contributions from all age groups.
The Longevity Economy: How Ageing Is Reshaping Business
Rethinking Work, Business and Opportunity in an Ageing World
Understanding the Longevity Economy
Population ageing presents a significant long-term change affecting the global economy. According to the United Nations Department of Economic and Social Affairs, the share of older persons is increasing across every region, particularly in developing countries. This demographic transformation shifts the intergenerational relationship, requiring working-age adults to support children and older relatives while older individuals contribute through employment and family support. The concept of a generational economy emphasizes the importance of understanding these exchanges as they play a critical role in shaping economic activity.
Another important dimension of this transformation is the changing relationship between age and economic participation. Longer life expectancy means that people may have more opportunities to learn new skills, change careers, establish businesses or remain professionally active beyond traditional retirement age. At the same time, longer lives can bring additional responsibilities related to healthcare, financial security and family care. These developments make the longevity economy relevant not only to older consumers, but also to employers, entrepreneurs and policymakers planning for the future.
The Rise of the Multigenerational Workforce
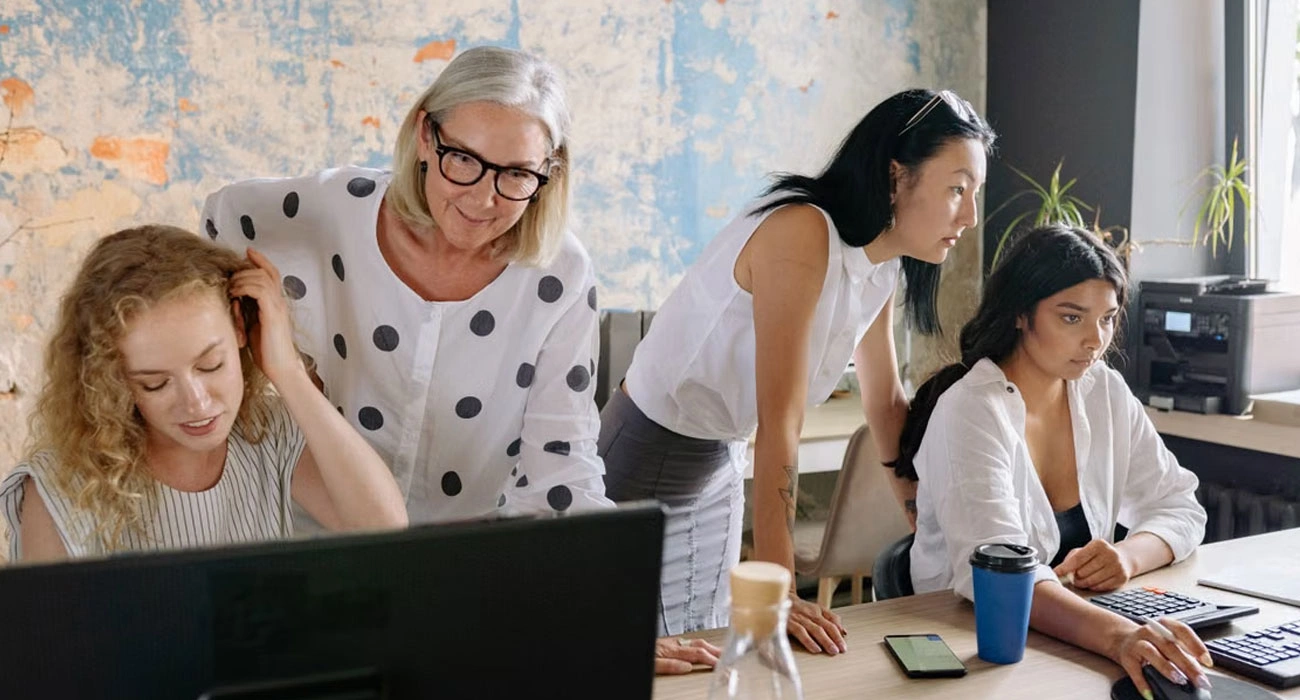
An ageing population challenges organizations to rethink how they attract, retain, and develop talent. Many workplaces now comprise employees from multiple generations, each bringing unique experiences and skills. Older employees contribute invaluable institutional knowledge and expertise, while younger employees offer fresh perspectives and technological skills. To capitalize on this diversity, organizations should foster an environment where skills are recognized regardless of age. Initiatives such as mentoring programs, continuous learning opportunities, and flexible career transitions can create a workplace culture that values intergenerational collaboration.
One practical way to strengthen this environment is through intergenerational knowledge exchange. Mentoring programmes can help younger employees gain professional insight from experienced colleagues, while reverse mentoring allows established professionals to learn about emerging technologies and changing workplace expectations. When organisations encourage these exchanges, experience becomes a shared resource rather than knowledge that remains limited to individual employees. This can support continuity, professional development and stronger collaboration across teams.
An ageing society is not simply a society with more older people. It is an economy in which generations become increasingly interconnected.— Inspiring Circle Editorial Team
- The United Nations DESA reported in October 2026 that population ageing is increasing across every world region, with particularly rapid transitions in many developing countries.
- UN DESA estimates that roughly half of GDP is transferred from earners to people of different ages across the countries examined through its generational economy framework.
- UN DESA's National Inclusion Accounts approach examines how resources are distributed across age groups and socioeconomic characteristics, including education, income, gender and migration status.
Building Businesses for Longer Lives
The longevity economy challenges businesses to think beyond short-term forecasts and adapt to changing consumer needs and workplace dynamics. Organizations must create inclusive workplaces that support individuals throughout different life stages, recognizing that demographic ageing affects people unequally. Successful adaptation will involve developing business models that provide opportunities for all generations, emphasizing experience, lifelong learning, and intergenerational cooperation. This approach can lead to sustainable long-term value and stronger communities, as societies invest in conditions that enable people of all ages to participate in economic activities.
The opportunities extend across several industries. Financial institutions can develop services that address longer retirement periods and changing savings needs, while healthcare providers can explore more integrated approaches to long-term wellbeing. Housing and technology companies can also create products that improve accessibility, independence and everyday convenience. For entrepreneurs, these developments represent opportunities to identify unmet needs and build services that respond to the realities of longer lives. The strongest business models will be those that combine commercial value with practical benefits for people across different age groups.
Categories
Image sources